Most first-time homebuyers in Florida feel stuck before they even start. You want a home, but the mortgage process looks confusing and overwhelming. This guide lays out a clear mortgage plan so you can prepare your finances, compare your loan options, and choose the best path with confidence using the Gen First Mortgage Method.
Build Your Mortgage Confidence
Feeling overwhelmed by the mortgage process is common, but you can build confidence with a clear plan. Let’s break it down into manageable steps, starting with setting your timeline and budget.
Set Your Timeline and Budget
The first step in your journey is to decide when you want to buy and how much you can afford. This involves considering your current financial situation and future goals. Start by listing your monthly income and expenses to see your surplus. This surplus will help determine your comfortable monthly mortgage payment. Consider any potential changes, like a job switch or a move, that might affect your timeline.
Next, think about the kind of home you want and what it might cost in your desired area. Research homes online or visit local open houses. Understanding the market will help you estimate how much you’ll need to save. Remember, being realistic and honest about your finances will set a strong foundation for your mortgage journey.
Strengthen Credit and Stabilize Income
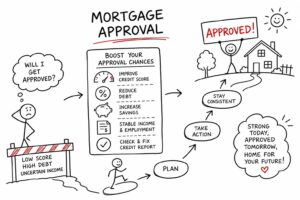
Your credit score is a key factor in mortgage approval. Many first-time home buyers might not realize how much their credit history impacts their loan terms. Start by obtaining a free credit report and checking for any errors. Pay off small debts and avoid late payments to improve your score over time.
Stabilizing your income is equally important. Lenders like to see consistent employment. If possible, avoid changing jobs during this period. Showing a stable income is crucial to strengthen your mortgage application.
Plan Down Payment and Reserves
Saving for a down payment might seem daunting, but with a plan, it’s achievable. Set a specific savings goal based on the loan type you’re considering. Many loans require 3% to 20% down. Also, aim to save enough for reserves, which are funds set aside for emergencies. This not only helps in the mortgage process but also provides peace of mind.
Consider exploring down payment assistance programs available in Florida. They can significantly reduce the amount of upfront cash you need. With a clear savings goal and potential assistance, you can make your homeownership dream a reality.
Explore Loan Options
Once your finances are in order, it’s time to explore your loan options. Understanding the different programs available will help you choose the right one for your needs.
Compare Loan Programs
Several loan programs are designed for first-time buyers, each with its pros and cons. FHA loans often require lower credit scores and down payments, making them popular. Conventional loans might offer better rates for those with strong credit. VA loans provide excellent benefits for veterans. USDA loans are available for rural areas.
Take the time to understand each option. Consider each loan type’s long-term impact on your financial situation. A mortgage advisor can help clarify which program aligns with your goals.
Get Pre-Approved the Right Way
Getting pre-approved is crucial. It shows sellers you’re a serious buyer and helps you know exactly how much you can afford. Gather all necessary documents like income statements and tax returns before applying. This preparation helps keep the pre-approval process running smoothly.
A pre-approval letter boosts your confidence when shopping for homes. It helps narrow down choices to what you can realistically afford, saving time and effort in your search.
Prepare for All Costs
Beyond the down payment, be aware of additional costs involved in buying a home. These include closing costs, which can range from 2% to 5% of the home price. Budget for these to avoid surprises.
Consider ongoing expenses like property taxes, homeowners insurance, and potential repairs. Planning for these ensures you’re financially ready for the full scope of homeownership.
The Gen-First Mortgage Advantage
Choosing the right mortgage guide can make all the difference. The Gen-First Mortgage Method provides personalized strategy and guidance.
Personalized Strategy and Guidance
With the Gen-First Mortgage Method, you receive a tailored plan that fits your unique needs. Isabelle Martinez works with you to understand your financial picture and future goals. This personalized approach means you’re never alone in the process.
Expect clear explanations of each step and what you need to succeed. This guidance is invaluable in navigating the complex world of mortgages.
Building Wealth Through Real Estate
Real estate is a powerful tool for building wealth. With the right mortgage plan, your home can be more than just a place to live. It becomes a financial asset that grows over time. The Gen-First Mortgage Method focuses on long-term strategy, ensuring your investment pays off for years to come.
Book Your Free Gen First Call 🌟
Ready to start your mortgage journey with confidence? Book a free call with Isabelle Martinez. During this session, you’ll discuss your goals, review your financial situation, and outline the next steps. Don’t wait your dream home is within reach.
Frequently Asked Questions
What is the ideal credit score for a mortgage?
Lenders often prefer a credit score of 620 or higher. However, FHA loans may accept lower scores. Improving your credit score before applying can secure better loan terms.
How much should I save for a down payment?
Aim for 3% to 20% of the home’s price, depending on your loan type. Explore down payment assistance programs in Florida for additional support.
What are closing costs in Florida?
Closing costs typically range from 2% to 5% of the home’s purchase price. These can include appraisal, title insurance, and lender fees.
How do I get pre-approved for a mortgage?
Gather documents such as income statements, tax returns, and bank statements. Contact a lender or mortgage advisor to start the pre-approval process.
What loan options are available for first-time home buyers in Florida?
First-time buyers can consider FHA, conventional, VA, and USDA loans. Each has different requirements and benefits, so choose one that fits your financial situation and future goals.