Buying your first home as a first-generation homebuyer in Florida can feel overwhelming. You might wonder what comes first, what lenders expect, and how to avoid costly errors. This guide lays out a clear mortgage pre-approval checklist so you can move forward with confidence and control. Let’s walk through the steps that make the Gen-First Mortgage Method your smartest path to approval and lasting wealth.
Understanding Credit and Finances
Getting a clear picture of your finances is the first step in the homebuying journey. Knowing where you stand empowers you to make informed decisions.
Credit Score for Mortgage
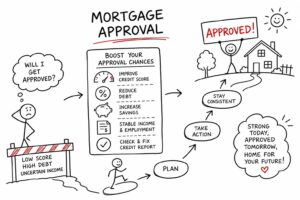
Your credit score reflects your borrowing history. A score above 620 is often needed for a mortgage. But don’t worry if yours is lower; there are steps you can take to improve it. Start by checking your report for errors. Pay down any high balances and make sure to pay bills on time. This shows lenders you’re reliable.
Debt-to-Income Ratio
Your debt-to-income ratio (DTI) measures the percentage of your income that goes toward paying debts. Lenders prefer a DTI below 43%. Calculate it by dividing total monthly debt by your monthly income. Keeping this number low shows you can handle new mortgage payments. If your DTI is high, consider paying off small loans to reduce it.
Managing Student Loans and Mortgage
Student loans are common, and they don’t have to stop you from getting a mortgage. Lenders look at your total monthly payments. If your student loans are manageable, they won’t block your approval. Consider income-driven repayment plans to lower monthly amounts if needed. By managing these wisely, you can balance both commitments.
Navigating Mortgage Options
Florida offers several mortgage choices. You’ll need to find the right fit based on your situation.
FHA Loan Florida vs Conventional Loan
FHA loans are popular with first-time buyers. They require a lower down payment and credit score. But they come with mortgage insurance. Conventional loans might need a higher credit score but can offer better terms without insurance if your down payment is 20%. Compare the two to see which best suits your needs.
Self-Employed Mortgage Florida
Self-employed? You can still get a mortgage! Lenders might require additional documentation, such as tax returns and business statements. Show consistent income over the past two years. This proves your financial stability. Preparing these documents ahead can speed up the process.
Gift Funds for Down Payment
Gift funds can help with your down payment. Family members can give you money to use towards buying a home. Check with your lender about rules. You’ll need a gift letter stating the money isn’t a loan. This boosts your buying power without adding debt.
Preparing for Pre-Approval

Pre-approval strengthens your buying position. It shows sellers you’re serious and ready to proceed.
Mortgage Documents Needed
Gathering the right documents is key. You’ll need pay stubs, bank statements, tax returns, and ID. These help lenders verify your financial status. Organizing these before applying can make the process smoother.
How to Get Pre-Approved
Getting pre-approved involves submitting your documents to a lender. They assess your credit and financial profile. This gives you a clearer picture of your borrowing power. It’s like getting a head start in the buying process.
Down Payment Assistance Florida
Florida offers programs to help with down payments. Look for state or local options that provide financial aid. These can ease the initial cost burden. Explore these resources to find what best fits your situation.
Frequently Asked Questions
What credit score do I need to buy a house in Florida?
You’ll typically need a credit score of at least 620, but some programs might allow for lower scores. Check with your lender for specific requirements.
How much should I save for a down payment?
Aim for 20% to avoid mortgage insurance, but many programs allow lower down payments. FHA loans, for instance, require as little as 3.5%.
Can I use gift funds for my down payment?
Yes, you can use gift funds. Ensure you have a gift letter from the donor confirming it’s not a loan.
What should I bring to get pre-approved?
Bring pay stubs, bank statements, tax returns, and identification. These help your lender assess your financial health.
Are there programs to help with down payments in Florida?
Yes, Florida offers down payment assistance programs. These can provide financial aid to ease initial costs.