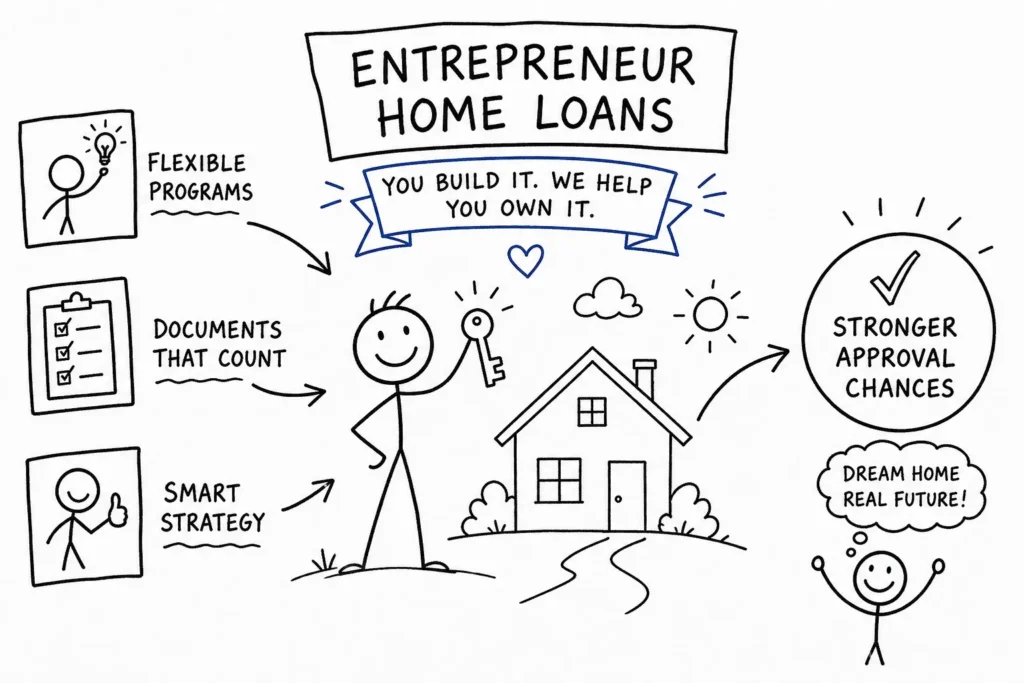
An entrepreneur home loan works very differently from a conventional mortgage, and understanding that difference is often what separates an approval from a denial. You built a business that generates real income. You pay your bills on time, keep healthy cash flow, and have more than enough to cover a mortgage payment. Then a lender pulls your tax returns, sees $48,000 in net income on a $300,000 gross revenue year, and denies you. That scenario plays out constantly for entrepreneurs, and it has nothing to do with financial irresponsibility. It has everything to do with a mortgage system designed around W-2 employees, not business owners.
The good news is that the gap has been acknowledged. Lenders offering bank statement loans, no-tax-return mortgages, and other non-QM mortgage programs have built entirely different underwriting frameworks specifically for people in your situation. At Isabelle Mortgages, we work with entrepreneurs and self-employed borrowers every week who were told “no” elsewhere and simply needed the right entrepreneur home loan matched to their actual financial picture. This article covers exactly that: the loan programs that fit self-employed borrowers, the specific documents lenders accept, how income gets calculated under each method, and the concrete steps you can take to improve your approval odds before you apply.
Why lenders treat entrepreneur income differently
The tax write-off trap
Every smart business owner reduces taxable income through deductions, home office expenses, vehicle use, equipment depreciation, software subscriptions, meals, and travel, and this is both legal and financially sound. The problem arises when a conventional lender looks at your Schedule C and sees $40,000 in net profit after all those deductions, even though $250,000 moved through your business account that year. Conventional underwriting uses your net taxable income, not your gross deposits, which can make a highly profitable entrepreneur look unqualified on paper.
The two-year self-employment rule
Most lenders require two full years of self-employment history before they’ll use that income for qualifying purposes. The reasoning is straightforward: they want to see that your business income is stable and not a one-time event. What many borrowers don’t realize is that some non-QM programs reduce this requirement to 12 months if you can show a strong prior W-2 track record in the same field. A consultant who spent eight years in corporate finance before going independent at the start of last year has a compelling case under those guidelines.
Why variable income raises lender flags
Traditional underwriting is built for predictability, and self-employment income is anything but linear. If your income increased from year one to year two, lenders average both years. If it declined, they use only the lower number. For a business that’s actively growing, the declining-year rule is particularly punishing because a strong current year gets ignored in favor of a weaker prior year. Understanding this before you apply helps you time your application strategically and choose the right program for your situation.
How an Entrepreneur Home Loan Qualifies Your Income
The tax return averaging method
When a lender uses your tax returns, they don’t simply take the bottom-line net profit number. They start with net profit from your two most recent federal returns, then add back specific non-cash deductions: depreciation, amortization, depletion, and home office expenses from Schedule C. The adjusted totals from both years are added together and divided by 24 to produce a monthly qualifying income figure. The add-back step is frequently overlooked by borrowers, and it can meaningfully increase the qualifying amount. An entrepreneur showing $60,000 in net profit but $25,000 in depreciation add-backs may qualify on closer to $85,000 in annual income.
The bank statement income formula
Non-QM bank statement programs use a straightforward calculation: total all deposits across 12 or 24 months, multiply by the income factor (which equals one minus the expense ratio), then divide by the number of months. Using real numbers: $300,000 in deposits over 12 months with a 50% expense ratio produces $12,500 in monthly qualifying income. If that same borrower’s tax return showed $40,000 in net income, the bank statement method generates $150,000 in annual qualifying income versus $40,000 under conventional underwriting. That difference determines whether you get approved and how much house you can buy.
Why the calculation method determines your loan amount
The same borrower qualifies for dramatically different loan amounts depending on which income method a lender uses. An entrepreneur with $250,000 in gross deposits and $40,000 in taxable net income will look entirely different under a bank statement program than under a conventional underwrite. Choosing the right program isn’t just a formality, it’s often the single factor separating an approval from a denial. Knowing how each method works before you apply lets you target the program where your actual earning power is fully recognized.
Loan programs built for self-employed borrowers
Bank statement loans
Bank statement loans are one of the most commonly used solutions for entrepreneurs who can’t qualify on tax return income. Instead of reviewing your federal returns, lenders collect 12 to 24 months of personal or business bank statements, total the deposits, and apply an expense ratio, commonly around 50% for business accounts, though programs vary, to arrive at a qualifying income figure. This approach reflects your actual cash flow rather than your tax-optimized net profit, which is a fundamentally different and more accurate picture of your ability to repay. For sole proprietors in lean service businesses with few employees, some non-QM lenders will lower that expense ratio to 20, 30%, which meaningfully increases qualifying income; specific program terms vary by lender, so confirm these thresholds directly.
Non-QM and P&L-based loans
Bank statement loans fall under the broader non-QM (non-qualified mortgage) category, which sits outside standard Fannie Mae and Freddie Mac guidelines. This gives lenders significantly more flexibility in how they evaluate borrower income. P&L loans use a CPA-prepared profit and loss statement as the primary income document, providing a real-time snapshot of business health without requiring filed tax returns. Asset depletion loans take a different angle entirely, converting liquid assets, savings, investment accounts, retirement funds, into a calculated monthly income figure. Home loans for self-employed borrowers exist in this space precisely because complex financial profiles don’t fit neatly into a standard application.
When a conventional or FHA loan still makes sense
Not every self-employed borrower needs a non-QM loan. If you have two years of tax returns showing strong net income even after deductions, a conventional loan offers lower interest rates and smaller down payment requirements. FHA loans can work well for business owners with credit scores in the 580, 620 range, as long as the net income on those returns clears the debt-to-income threshold. The first question to ask before exploring non-QM is whether your documented income, with proper add-backs, could qualify you conventionally. Running that calculation first can save you the rate premium that comes with non-QM programs.
Documents for an Entrepreneur Home Loan
Core documentation for non-QM and bank statement loans
If you’re pursuing an entrepreneur home loan through a bank statement or non-QM program, lenders typically require 12, 24 months of personal or business bank statements, a CPA-prepared year-to-date P&L statement, a business license or registration showing active operation, and a CPA letter confirming your self-employment status.
For conventional or FHA loans, the document set shifts considerably. Two years of signed federal tax returns are required, including Schedule C for sole proprietors, Schedule K-1 forms if you own 25% or more of a partnership or S-corp, and the associated business returns. Keep in mind that 1099 forms are supplemental documentation, not standalone proof of income. Treating them as sufficient is one of the most common mistakes self-employed applicants make.
Supporting documents that strengthen your application
Beyond the required documents, a well-organized supporting package signals credibility and speeds up the process. Prior-year business tax returns beyond the two-year window show income history and trend. Bank statements demonstrating consistent deposit patterns month over month reduce lender concern about income volatility. Asset and reserve documentation matters significantly for non-QM loans, where lenders often require 6, 12 months of liquid reserves after closing. For freelancers and consultants, evidence of long-term client contracts reinforces income stability. A clean, complete document package reduces back-and-forth requests and helps close loans faster.
What to expect: rates, down payments, and costs
Non-QM versus conventional loan cost comparison
In mid-2026, conventional 30-year fixed mortgage rates are hovering in the 6, 7.5% range, according to current market surveys. Non-QM bank statement loans carry a premium of 0.5, 2 percentage points above that, placing most borrowers between 7% and 10% depending on credit score, loan-to-value ratio, and lender. The rate reflects lender risk: without tax-return verification, they’re pricing in uncertainty. One meaningful offset is that many non-QM programs waive PMI even at 85% LTV. For a borrower putting 15% down on a $450,000 home, eliminating a PMI payment, which can run $150, $300 per month depending on loan size and insurer, partially compensates for the rate difference in total monthly cost.
Down payment realities for self-employed borrowers
The 3, 5% down payment programs you see advertised are rarely accessible to self-employed borrowers because income verification typically doesn’t meet the requirements. For non-QM bank statement loans, many lenders require roughly 10% down with top credit scores (often 720+) on a primary residence, rising to 15, 20% for scores in the 680, 720 range, and 20, 25% for lower scores or investment properties, though specific thresholds vary by lender and program. Putting 20% down on a non-QM loan can bring rates meaningfully closer to conventional territory and eliminates PMI entirely. If your cash reserves allow it, a stronger down payment is one of the most effective levers for reducing the total cost of a non-QM mortgage.
Concrete steps to improve your approval odds
Prepare your financial profile before applying
The six to twelve months before you apply are your best opportunity to shape what lenders see. Work with your CPA to evaluate whether strategically reducing business deductions this tax year would increase your qualifying income enough to justify the tax difference. Build liquid reserves to satisfy the 6, 12 month post-close threshold most non-QM lenders impose. Maintain consistent deposit patterns in your business account and avoid large undocumented transfers, which lenders flag as potential income irregularities. A credit score of 720 or higher unlocks better rates and lower down payment thresholds across most non-QM programs, getting there before you apply can save tens of thousands over the life of the loan.
Working with a lender who understands your situation
Entrepreneurs don’t just need a loan officer who can take an application. They need someone who can read a complex financial profile, identify which program maximizes qualifying income, and guide the documentation process without creating unnecessary delays or confusion. Most conventional lenders simply aren’t built for this.
At Isabelle Mortgages, the entire process is structured around borrowers with non-traditional income. The Gen-First Mortgage Method™ maps out the right path from the first conversation: which program fits your income structure, which documents to gather, and how to present your financial story in the way lenders respond to. You’ll have one-on-one guidance, transparent timelines, and consistent communication throughout, because for a borrower navigating a complex application, clarity at every step isn’t a bonus, it’s the standard.
The right entrepreneur home loan makes the difference
Qualifying for a home loan as an entrepreneur comes down to matching the right program to your specific income structure. Bank statement loans solve the tax-return problem by qualifying you on actual cash flow. Non-QM options, including P&L loans, stated income loans, and asset depletion programs, expand your choices further. Having the right documents ready before you apply reduces friction and speeds the process. And understanding how lenders calculate income under each method puts you in control of which program gives your earning power the best chance of being fully recognized.
If your income doesn’t fit a standard mortgage application, the practical next step is a direct conversation about which program fits your profile. Contact Isabelle Mortgages for a free consultation, bring your last 12, 24 months of bank statements, your most recent P&L, and a general sense of what you’re trying to buy. From there, the path to approval becomes a clear process rather than a guessing game.
Homeownership is a real and achievable goal for entrepreneurs who approach it strategically. The system has gaps, but the right programs and the right partner close them.
Frequently Asked Questions About Entrepreneur Home Loans
What is an entrepreneur home loan?
An entrepreneur home loan is a mortgage designed for self-employed borrowers and business owners whose income doesn’t fit standard W-2 documentation requirements. These loans, including bank statement loans, P&L loans, and other non-QM programs, qualify borrowers based on actual cash flow, CPA-prepared statements, or liquid assets rather than net taxable income.
How many months of bank statements do I need for a self-employed mortgage?
Most bank statement loan programs require 12, 24 months of personal or business bank statements. Twelve months is the minimum for many lenders; 24 months provides a stronger qualifying picture and may open up better rates or lower down payment requirements depending on the program.
Can I get a no-tax-return mortgage as a business owner?
Yes. Several non-QM programs, including bank statement loans and P&L loans, do not require filed tax returns as the primary income documentation. These no-tax-return mortgage options are specifically designed for borrowers whose returns understate actual cash flow due to legitimate business deductions.
What credit score do I need for a non-QM entrepreneur home loan?
A score of 720 or higher positions you for the best rates and lowest down payment requirements across most non-QM programs. Scores in the 680, 720 range are generally workable but typically require higher down payments. Requirements vary by lender and program type, so it’s worth reviewing your options with a lender experienced in non-QM financing.