Finding the right property is only half the equation. If you’re asking what are the best loan options for real estate investors, the financing structure you choose is where the real answer lives, it determines whether a deal builds your portfolio or quietly bleeds cash flow month after month. The wrong loan can erode your returns, slow your close time, or disqualify you from a contract entirely before you even get to the inspection.
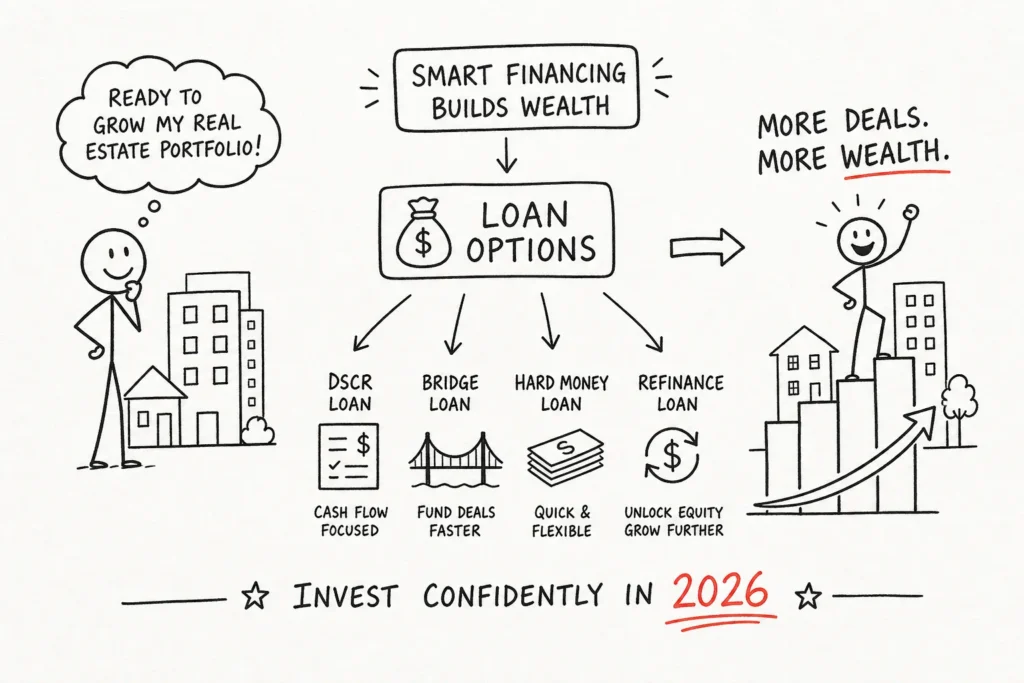
In 2026, investors have a wide range of rental property financing and investment property loan options to work with: DSCR loans, hard money, portfolio loans, HELOCs, cash-out refinances, and conventional investment mortgages. That variety is genuinely useful, but it also creates decision paralysis for investors who aren’t sure which structure fits their situation.
At Isabelle Mortgages, we work with investors at every stage of their portfolio, from the first rental to the fifth, and the question we hear most often is: what’s the right loan for my situation? This guide breaks down each major loan type, who it’s built for, what it costs, and where it fits in a real investment strategy.
Conventional Investment Property Loans: The Reliable Baseline
Conventional mortgages are where most investors start. Rates are competitive, 30-year fixed terms are widely available, and the loan programs are backed by Fannie Mae and Freddie Mac guidelines that most lenders understand and process efficiently. But the qualification bar for investment properties is meaningfully higher than what first-time homebuyers experience on a primary residence.
What Lenders Actually Require for an Investment Property
The minimum down payment for a single-family rental is 15%, compared to the 3% to 5% many buyers put down on a primary home. Most lenders also require roughly six months of cash reserves on top of your down payment, so your liquidity needs add up quickly. DTI is typically capped around 43% to 45%, and lenders want to see you can carry the full mortgage payment even before rental income factors into the calculation.
Documentation requirements are thorough: W-2s, two years of federal tax returns, and Schedule E documentation for any existing rental properties you already own. Credit score requirements vary by lender and program, many seek 620 to 680 at minimum, with scores at or above 680 commonly associated with more competitive pricing. Lenders want a clean, verifiable income picture before they’ll approve an investment purchase.
The Real Pros and Cons for Rental Investors
The primary advantage of conventional financing is cost. Rates are lower than DSCR or hard money loans, and 30-year fixed terms give you payment predictability that makes long-term cash flow modeling straightforward. For a buy-and-hold investor with a W-2 job and a manageable debt load, conventional financing is almost always the most cost-effective entry point.
The limitations show up quickly, though. Strict income documentation and DTI sensitivity mean that as you add more properties, your debt exposure grows and qualifying becomes harder. Self-employed investors with variable income often find that their tax returns, optimized for deductions, show less income than they actually earn, creating a disconnect between their real financial strength and what the lender can see on paper.
When Conventional Financing Stops Working
Fannie Mae and Freddie Mac guidelines tighten significantly once you carry four or more financed properties. Around five financed properties, many investors find they’ve outgrown agency programs, and portfolio or DSCR options become the more practical path forward. This is the natural inflection point where investor-focused financing structures take over for active investors building real portfolios.
What Are the Best Loan Options for Real Estate Investors Who Are Self-Employed? DSCR Loans Explained
Debt service coverage ratio loans have become widely used, and increasingly the preferred tool, among serious real estate investors. They shift the qualification logic entirely: instead of evaluating your personal income, the lender evaluates whether the property itself generates enough rent to cover the mortgage payment. For self-employed investors, 1099 earners, and anyone whose tax returns don’t reflect their actual earnings capacity, this is a significant advantage.
How DSCR Qualification Actually Works
The DSCR formula is straightforward: monthly gross rent divided by total monthly debt service (principal, interest, taxes, insurance, and any HOA fees). A DSCR of 1.0 means rent exactly covers the payment; a DSCR of 1.25 means rent covers 125% of the payment, which is the threshold most lenders associate with better pricing and easier approval.
Many DSCR programs require limited personal income documentation, in some cases, no W-2s, tax returns, or personal DTI calculation, letting the property’s income do the qualifying work. Requirements vary by lender and program, so confirm specifics with your advisor before assuming your file will qualify on property income alone. Most standard programs require a DSCR of 1.00 to 1.20 at minimum, with 1.25 being the sweet spot for competitive terms. Some niche lenders offer “no-ratio” or sub-1.0 DSCR programs, but expect tighter terms and higher rates on those files. Short-term rental investors using Airbnb or VRBO income can qualify in many programs, though lenders handle STR income documentation differently, so confirm before assuming projected rents will count.
2026 Rate and Underwriting Benchmarks
As of mid-2026, DSCR loan rates are running approximately 6.25% to 8.00% for most borrowers. Strong files, credit scores above 700, loan-to-value ratios at or below 75%, and DSCR above 1.25, are landing closer to the 6.25% to 7.50% range. Weaker credit, higher leverage, or riskier property types push rates toward the 8%+ tier. For additional context on current DSCR loan rates, see industry rate summaries and lender updates.
LTV limits are typically 80% on purchases and 75% on cash-out refinances. Most programs set a minimum credit score of 640 to 660, though pricing improves meaningfully above 700 and again above 720. If you’re building a DSCR file, prioritize getting your credit score above 720 before applying. The rate differential between a 660 and a 720 score can meaningfully affect your total borrowing cost over the life of the loan. For a broader look at investment property loan rates and requirements, consult reputable market analyses and guides.
Who DSCR Loans Are Built For
DSCR loans are the right tool for three distinct investor profiles:
- Self-employed investors and 1099 earners who can’t qualify on paper through conventional underwriting
- Portfolio builders financing multiple properties simultaneously
- Investors who want to scale without their personal DTI becoming the ceiling on their growth
The key requirement is that your properties need to perform. If rent doesn’t cover the payment, the loan doesn’t underwrite, so this structure rewards investors who buy with cash flow in mind from the start.
Hard Money and Bridge Loans: When Speed Is the Strategy
Hard money and bridge loans are tactical financing tools, not long-term holds. They exist to solve a specific problem: getting capital deployed fast when a deal requires speed that conventional underwriting can’t match. Understanding what they cost, and what they’re designed for, is the difference between using them as a smart lever and getting burned by the carry costs.
The Core Logic Behind Asset-Based Lending
Hard money lenders underwrite the property, not the borrower’s income or credit score. That shift in underwriting logic is what enables closings in 10 to 25 days versus the 30 to 60 days conventional loans typically require. Loan terms typically run 6 to 18 months, with some lenders extending to 24 months on larger or more complex projects. LTV is generally capped at 65% to 80% of purchase price or after-repair value (ARV) for fix-and-flip projects. For a deal that would expire before conventional financing could close, hard money is the mechanism that keeps you in the game.
What Hard Money Really Costs
Interest rates for hard money loans typically range from 8% to 14%, with some lenders going higher, toward 18%, on riskier deals or weaker borrower profiles. Origination fees (called points) commonly add another 1% to 5% upfront, which is a real cost on any deal: on a $300,000 loan, three points is $9,000 paid before you’ve done a single repair. The math only works if your exit is fast. Carrying a 12% interest-only loan for six months eats profit quickly, so every hard money deal needs a clearly defined exit before you borrow.
Fix-and-Flip vs. Bridge to Permanent Financing
For fix-and-flip investors, hard money is the standard tool: buy the distressed property, fund the renovation, sell, and repay the loan at closing. The short term is a feature, not a limitation, because the exit is designed to happen fast. For buy-and-hold investors, hard money functions as a bridge, close quickly on an underpriced deal, stabilize it, and refinance into a DSCR or conventional loan once the property qualifies for permanent financing. Any buy-and-hold investor using hard money needs a confirmed refinance exit strategy before they sign the note. Without it, the carry cost can eliminate the deal’s return entirely.
Portfolio Loans, HELOCs, and Cash-Out Refinances: Flexible Capital for Growing Investors
Once you’ve scaled past the limits of conventional underwriting, or you want to leverage existing equity without disrupting your current financing, these three tools offer distinct paths forward. Each one serves a different capital deployment scenario, and knowing which one fits your position is worth more than any rate shopping.
Portfolio Loans: When You’ve Outgrown Conventional Limits
Portfolio loans are mortgages that lenders keep on their own books rather than selling to Fannie Mae or Freddie Mac. Because the lender holds the risk, they write their own qualification rules. That flexibility is the product: investors with five or more financed properties, non-warrantable condos, mixed-use assets, or complex income structures can often qualify for portfolio financing when conventional doors are closed. Rates commonly run modestly higher than conventional rates, reflecting the lender-held risk, but for investors who need the deal, that premium is the cost of access rather than a red flag. For a practical primer on managing a growing rental portfolio and available financing options, see this overview of rental portfolio loans.
Using a HELOC to Fund Your Next Investment Purchase
A HELOC on a primary residence lets you tap existing equity as a revolving line of credit, drawing what you need and repaying it as deals close. Lenders generally require 15% to 20% equity remaining after the draw, a credit score around 660 to 680 or higher, and a DTI in the 36% to 43% range. The flexibility is the advantage: you only pay interest on what you’ve actually drawn, which makes it well-suited for investors who want to deploy capital in stages or need a fast-access liquidity bridge. The variable rate is the main risk, your effective borrowing cost can shift as the rate environment moves. For lender-specific guidance on HELOC eligibility, review bank underwriting criteria and example scenarios.
Cash-Out Refinance: Lump-Sum Equity Deployment
A cash-out refinance replaces your existing mortgage with a larger loan and delivers the difference in cash at closing. It’s better suited to one-time large capital needs, like a significant down payment or a property purchase where you want payment predictability on both the new and existing debt. The key tradeoff is structural: you’re resetting your mortgage timeline, increasing your principal balance, and committing to a fixed payment. It makes the most sense when the return you’re targeting on the deployed capital clearly exceeds your new borrowing cost, and when you’re comfortable with the full picture of your monthly obligations after the refinance closes.
What Are the Best Loan Options for Real Estate Investors? How to Match Loan Type to Strategy
The investors who make the best financing decisions aren’t always the ones with the best credit or the most capital. They’re the ones who match their loan structure to their strategy before they go under contract, not after. Getting this right requires thinking through four variables: your income type, your investment strategy, your timeline, and your existing debt exposure.
The Decision Matrix Most Investors Skip
A simplified mapping of the best loan options for real estate investors looks like this:
- W-2 income and a first rental property, points toward conventional financing
- Self-employed income and multiple rentals, points toward DSCR loans
- Fast acquisition on a value-add property, points toward hard money or bridge financing
- Five or more financed properties, points toward portfolio loans
- Existing equity you want to leverage, points toward a HELOC or cash-out refinance
Investors who skip this analysis often take the first loan they get approved for, which is rarely the one that optimizes their actual return.
Why the Loan Structure Affects Your Long-Term Portfolio Math
Rate differentials, origination points, and reserve requirements all affect your cash-on-cash return on every deal you close. A DSCR loan that closes in 30 days on a deal you’d lose under conventional underwriting timelines can outperform a slightly lower rate that costs you the contract. Equally, choosing hard money when a DSCR loan would have worked means carrying 10%+ interest through a hold period that didn’t require that speed. The loan structure you choose at one stage also shapes what you can finance next: burning through reserves on points and origination fees limits your deal capacity going forward.
Working with a Specialized Mortgage Advisor to Build Your Loan Strategy
At Isabelle Mortgages, we specialize in helping real estate investors identify the right loan structure based on income type, portfolio size, and deal timeline, not just what’s easiest to approve. That distinction matters: a generalist lender processes loans; an investor-focused advisor helps you think through the structure before the deal is even under contract, so you’re not reverse-engineering a financing plan under time pressure. For concrete examples on how investors can use mortgage structures to build long-term wealth, read Investment Loan Property: Build Generational Wealth.
The practical difference shows up in things like knowing when to stack a HELOC with a DSCR loan, understanding how to document 1099 income for a stronger DSCR file, or recognizing when a bridge loan with a clear refinance exit is the right play versus when it’s unnecessary risk. If you’re unsure about documenting irregular income, see our guide on qualifying for a mortgage with overtime and multiple jobs for practical documentation tips that translate to investor situations as well. If you’re ready to discuss your next deal or want to map out your loan strategy for the next 12 months, schedule a consultation with our team and we’ll start with your specific portfolio scenario.
The Financing Decision That Separates Good Deals from Great Ones
The best loan options for real estate investors aren’t universal. The right choice depends on what you own, how you earn, how fast you need to move, and what stage of portfolio growth you’re in. There’s no single right answer, but there are clearly wrong ones: financing a long-term hold with hard money and no exit plan, qualifying conventionally when DSCR would unlock a better deal structure, or tapping a HELOC without accounting for the variable-rate risk on your primary residence.
In 2026, investors have genuine options across rental property financing and investment property loans: conventional loans for clean income profiles, DSCR for properties that can carry themselves, hard money for speed and renovation plays, portfolio loans for scaled investors who’ve outgrown agency guidelines, and equity-based options for those with existing assets to leverage. Each one has its place, and the right combination depends entirely on your situation.
The investors who win aren’t always the ones with the most capital. They’re the ones with the right financing structure at the right time. If you’re still asking what are the best loan options for real estate investors, and how to apply that answer to your specific deals, schedule a consultation with Isabelle Mortgages and we’ll map the right strategy for your portfolio. For ongoing insights and articles on investor financing, visit our Blog, Isabelle Mortgages.